
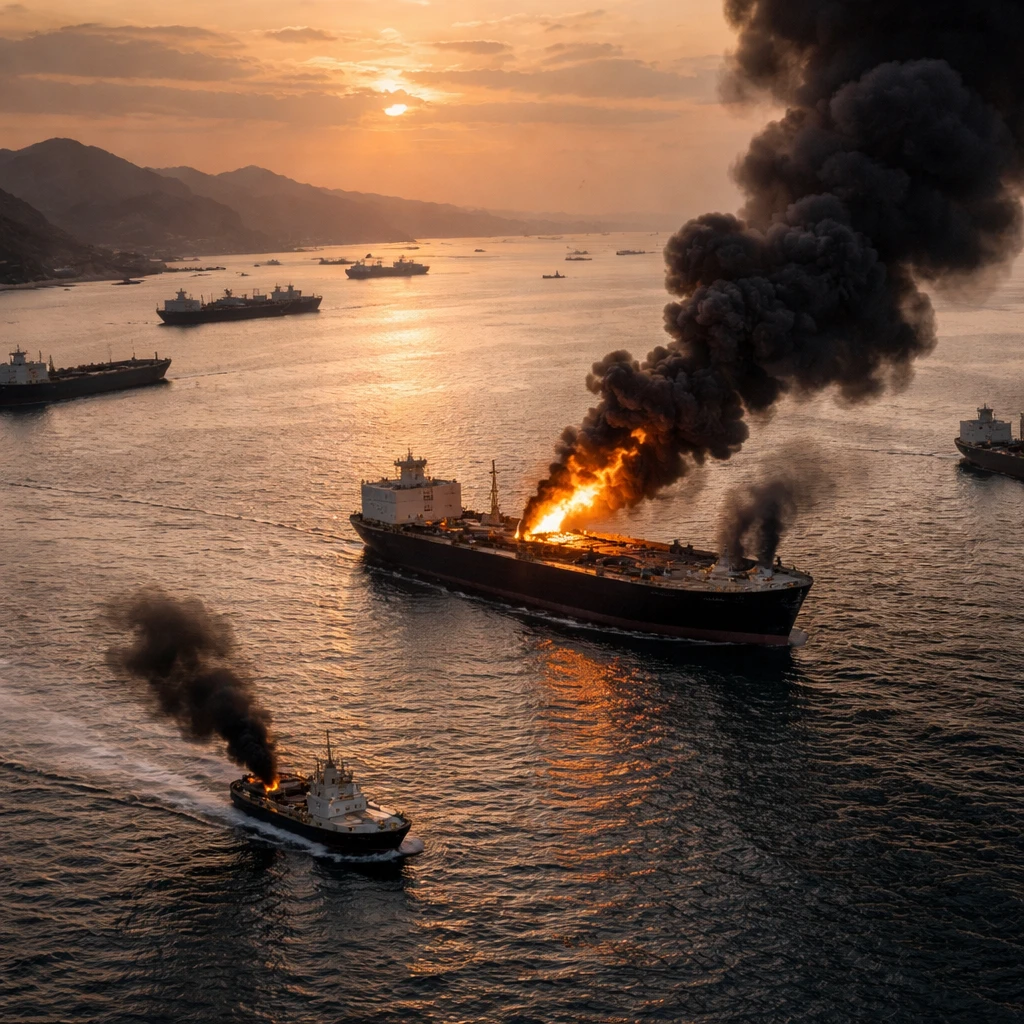
European wholesale natural gas prices continued to slide on Thursday, adding to a rapid three-session unwind after a dramatic sell-off in global crude benchmarks weakened the energy complex's previously elevated risk premium. The downward pressure on gas came despite fresh accounts of maritime incidents in the Strait of Hormuz.
Market moves
The benchmark Dutch Title Transfer Facility (TTF) front-month contract dropped another 1.6% to 86.60 euros per megawatt-hour (MWh). That decline followed several sessions of heavy selling and left the contract roughly 20% lower over the past three trading days.
Across the Channel, Britain’s National Balancing Point (NBP) front-month contract fell 1.7% to 214.74 pence per therm, mirroring a broader deflationary trend moving through European power and heating curves.
Oil rout overrides geopolitical headlines
Brent crude futures plunged nearly 9% overnight, breaching the psychological $100 mark and trading well into double digits. The move put Brent about 20% lower for the week so far - a fall that, if it persisted to Friday’s close, would represent the single largest weekly decline in oil prices since April 2020, when pandemic lock-downs briefly pushed some U.S. crude benchmarks into negative territory.
For European gas desks, that collapse in oil has effectively severed the inflationary feedback loop that had pushed forward curves higher through October. As oil-linked liquefied natural gas (LNG) import contracts and spot replacement fuels fell in price, institutional allocators have aggressively reduced emergency supply hedges.
Market participants cited the twin effects of cheaper replacement fuels and a perceived reduction in the immediate risk of a wider U.S.-led military escalation against Iran, a view they attribute to the altered political balance in the U.S. Congress. That assessment encouraged allocators to unwind geopolitically driven positions.
Maritime incidents and transit data
Iran’s Islamic Revolutionary Guard Corps (IRGC) said on Thursday that two oil tankers and a tugboat had caught fire in separate incidents after attempting to navigate "unauthorised routes" through the Strait of Hormuz. While the report underlines ongoing hazards facing merchant shipping in the region, trading desks treated the episodes largely as localized operational disruptions rather than evidence of a systematic blockade.
Commodity tracking sources and maritime analysts report that crude shipments through the chokepoint have recovered to levels close to those seen before recent hostilities. That recovery in physical flows, combined with the oil price rout, has reduced prompt panic among buyers even as shipping firms and major energy companies continue to face elevated war-risk insurance premiums and higher security escort costs.
Storage and structural dependence
European Union underground natural gas storage facilities stood at 74% of capacity - a level described in market commentary as a historically thin buffer for early November. The rebound in Gulf transit volumes and the steep decline in crude prices have eased immediate prompt-market pressures, but Europe remains heavily reliant on steady imports of Atlantic and Middle Eastern LNG to offset structural pipeline shortfalls.
Implications for markets
Traders shifted attention from the new Gulf incidents to resilient maritime transit statistics and the rapid repricing across oil and fuel markets. The combination of lower oil-linked fuel costs and a perceived reduction in escalation risk prompted aggressive unwinding of geopolitically motivated hedges, accelerating the gas sell-off.
While the current moves reflect a reassessment of short-term geopolitical risk, the underlying dependence on LNG flows and suboptimal storage levels leave European gas markets exposed to renewed shocks should transit conditions or market sentiment change.