
Summary
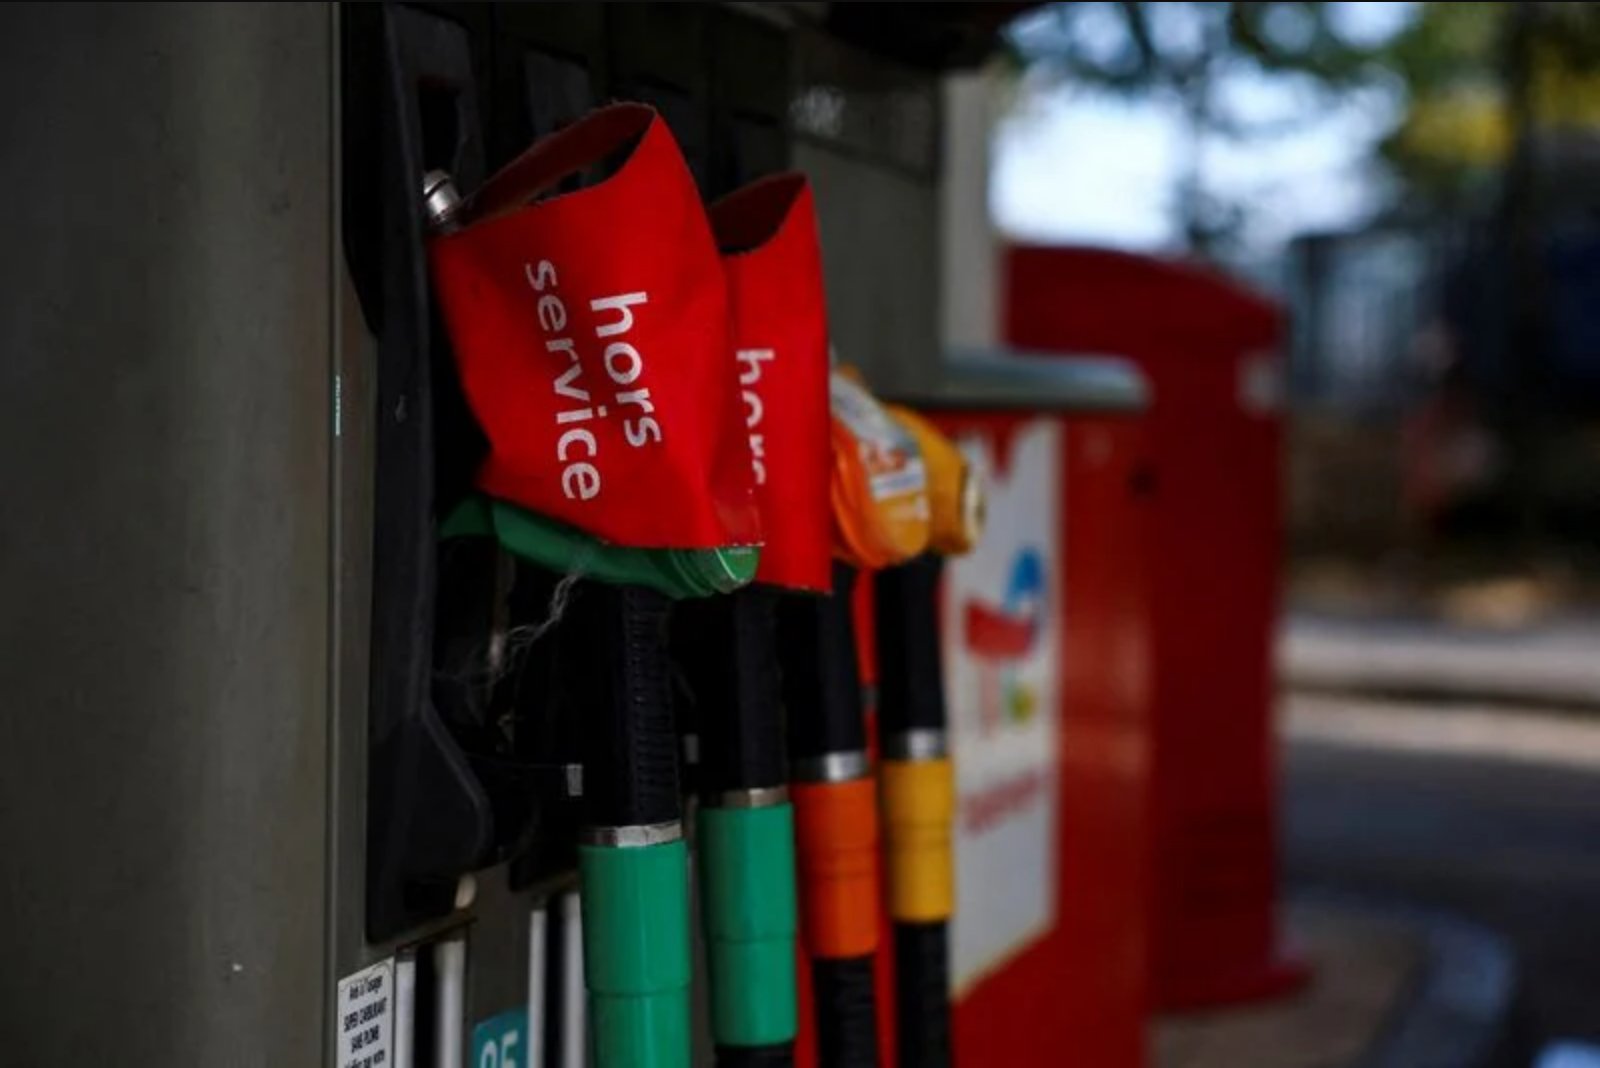
Global diesel markets have tightened sharply, with prices in Europe, the United States and Asia reaching record or near-record levels. A succession of supply disruptions tied to conflicts in the Middle East and Ukraine has cut exports from major producers and left refiners operating at high rates. Industry and shipping data show inventories and flows under pressure, and analysts warn that limited spare refining capacity could allow prices to rise further if disruptions continue.
Market developments
Diesel futures in Europe ended last week at an all-time high, having more than doubled since the start of 2026 as supply constraints spread to key loading routes, including the Red Sea where Saudi Arabia ships most of its diesel. The wars in the Middle East and in Ukraine have damaged oil refining infrastructure in affected regions and forced refineries elsewhere to operate at elevated throughput to try to replace lost output.
For example, the International Energy Agency reported that U.S. refineries ran at their highest rates in eight years in late August, reflecting the premium placed on producing transport fuels. The agency also highlighted a limited ability to increase output further, noting: "A key issue is that many refineries around the world are already stretched to capacity." The IEA said this constraint leaves few options to prevent further tightening of supplies and higher prices in the coming months.
Supply flow and inventory data
Shipping data from Kpler indicate that Middle East diesel exports averaged about 800,000 barrels per day from March to August, roughly half the volumes seen in the same period a year earlier. The region supplied nearly 41% of Europe’s diesel imports in 2025, according to Kpler data, underscoring the significance of those flows to European fuel balances.
Kpler analyst George Shaw warned: "Any further disruption to Red Sea flows risks tightening an already stretched global diesel market," and added that global diesel markets remain vulnerable as refining capacity continues to be the key pinch point.
Russia and other supply changes
Russia instituted a ban on diesel exports in July after Ukrainian drone attacks reduced Russian refinery output. The two countries have continued to attack each other’s energy infrastructure despite an announcement by U.S. President Donald Trump last week that they had agreed to stop. Ukrainian President Volodymyr Zelenskiy said on Sunday he will meet with Trump in the coming days.
Before the ban, Russia was supplying substantial volumes of diesel to markets including Turkey and Brazil. Russia is reported as the world’s second biggest diesel exporter after the United States, and the export ban pushed buyers to seek alternative sources.
Regional price and inventory snapshots
In the United States, average retail diesel prices moved above $6 a gallon for the first time on record this month. U.S. inventories have increased by roughly 600,000 barrels in the last reported week to stand at 96.97 million barrels, but these stocks remain nearly 15% below the five-year average for the second week in September despite refiners operating near capacity.
In Europe, stocks at the Amsterdam-Rotterdam-Antwerp hub were at their lowest level for this time of year on September 10, according to data from Insights Global. Asia has also seen elevated diesel prices, with diesel swaps - a benchmark for the region - having eased from a March record high of more than $200 a barrel to around $180 a barrel on September 18. Those levels are still about double pre-war values.
China’s role
China reduced diesel exports substantially in the aftermath of the Iran war after a government decision to limit refined product shipments, with exports falling 26% in April-June from a year earlier. However, China’s exports recovered and reached 320,000 barrels per day in August, the highest level in nearly two and a half years, a rebound that contributed to lower Chinese domestic stocks.
What this means for markets and users
The combination of damaged refining infrastructure in conflict zones, export curbs and restrained spare refining capacity has left diesel markets with little margin for error. Refineries in other regions have been pushed to produce more, but the IEA and market analysts caution that global refining limits are a central constraint. That dynamic has driven wholesale and retail diesel prices higher and left inventories at key hubs and nationally below seasonal norms.
Given the current configuration of supply and demand, further disruptions along major shipping routes or additional refinery outages could push prices higher, while the ability of refiners to respond is limited by capacity constraints.
Data and quotes referenced
- European diesel futures closed at an all-time high last week and have more than doubled since the start of 2026.
- Middle East diesel exports averaged 800,000 barrels per day from March to August, about half the year-earlier level, according to Kpler.
- Middle East accounted for nearly 41% of Europe’s diesel imports in 2025, per Kpler.
- U.S. refineries ran at their highest level in eight years in late August, according to the IEA.
- U.S. average retail diesel prices rose above $6 a gallon for the first time on record this month.
- U.S. diesel stocks rose by roughly 600,000 barrels last week to 96.97 million barrels, nearly 15% below the five-year average for the second week in September.
- Asian diesel swaps eased from a March peak above $200 a barrel to around $180 a barrel on September 18, roughly twice pre-war levels.
- China’s diesel exports fell 26% in April-June year on year, then recovered to 320,000 bpd in August.
Reporting and analysis reflect shipping, inventory and market commentary available in the public record. The situation remains fluid given ongoing conflicts and constrained refining capacity.