
Overview
Markets entered the week with sovereign debt tensions front and center, driven by a confluence of rising political risk in Europe, renewed instability in the Middle East and headline-grabbing corporate financing tied to AI-related expansion. These forces left bond markets taut and raised the question of whether equities can continue to look through higher yields and energy price swings.
Europe: sovereign spreads and politics
European bond markets were a focal point as the gap between French and German 10-year yields widened past 140 basis points - the largest divergence since 2012 - reflecting investor preference for perceived safe-haven German Bunds over debt from more heavily indebted members of the bloc. French policymakers have put forward a 2027 budget that aims to reduce the country’s deficit to 5% from an expected 5.4% this year, but navigating that plan through a deeply divided parliament and amid widespread domestic protests - including demonstrations over education funding and other issues - adds uncertainty ahead of next year’s presidential election.
France is not alone in facing a fractious political environment. Spain’s prime minister called a snap election for November 29 in an effort to secure a parliamentary majority, a move described as a gamble given centre-left polling weakness. The aggregation of these political stresses, combined with bond market strains, has contributed to downward pressure on the euro, which touched a 17-month low of $1.1161 on Monday before a modest rebound.
For the European Central Bank, this mix complicates policy choices. Markets still expect another rate increase before year-end as euro zone inflation remains sticky around 3.8%, but policymakers may be wary of further unsettling sovereign markets while elevated energy costs persist.
Energy: oil swings, supply risks and logistics premium
Energy markets added to the nervousness. Brent crude slipped early in the week amid reports that flows out of the Gulf were returning toward pre-conflict levels, but the optimism was short-lived. On Thursday, Brent jumped 4% to trade above $104 a barrel as Iranian strikes on ships in the Strait of Hormuz intensified and as Yemen’s Iran-aligned Houthi group attacked vessels in Saudi waters. Prices eased somewhat on Friday after President Donald Trump said the United States would not attack Iran before the midterm elections, but Brent remained on pace for a weekly gain.
Efforts to increase supply through strategic releases also produced only muted market relief. The International Energy Agency agreed to accelerate the release of oil, prioritizing diesel, under a plan launched in March to address record-high fuel prices, but the market response was limited. The muted reaction illustrates a new dynamic in the energy complex: even if crude exports from the Gulf approach pre-conflict volumes or global shipments pick up, fuel prices may stay elevated because of a substantial geopolitical risk premium and costly logistical constraints associated with moving oil out of the Middle East.
Adding to supply-side disruptions, Hurricane Isaias has already impacted oil and gas production in the Gulf of Mexico and was moving toward the US Gulf Coast, creating additional short-term operational risk for regional output.
United States: Treasuries, the Fed and yield moves
Across the Atlantic, expectations for a Federal Reserve rate increase in October retreated sharply last week amid softer economic readings and less-hawkish commentary from New York Fed leadership. Nonetheless, the minutes from the September FOMC meeting released midweek, along with remarks from Fed Governor Christopher Waller, signalled that the central bank has not finished tightening and could resume hikes even if officials stand pat this month.
Long-dated US yields were the real story. The benchmark 10-year Treasury yield climbed to a fresh 24-year high, briefly reaching 5.364% on Wednesday before easing after strong demand at a 30-year Treasury auction; that longer-dated debt reportedly cleared at the highest yield seen since 2000. These moves at the long end of the curve have important implications for financing costs across the economy and for asset allocations.
Equities, AI revenue signals and the upcoming earnings season
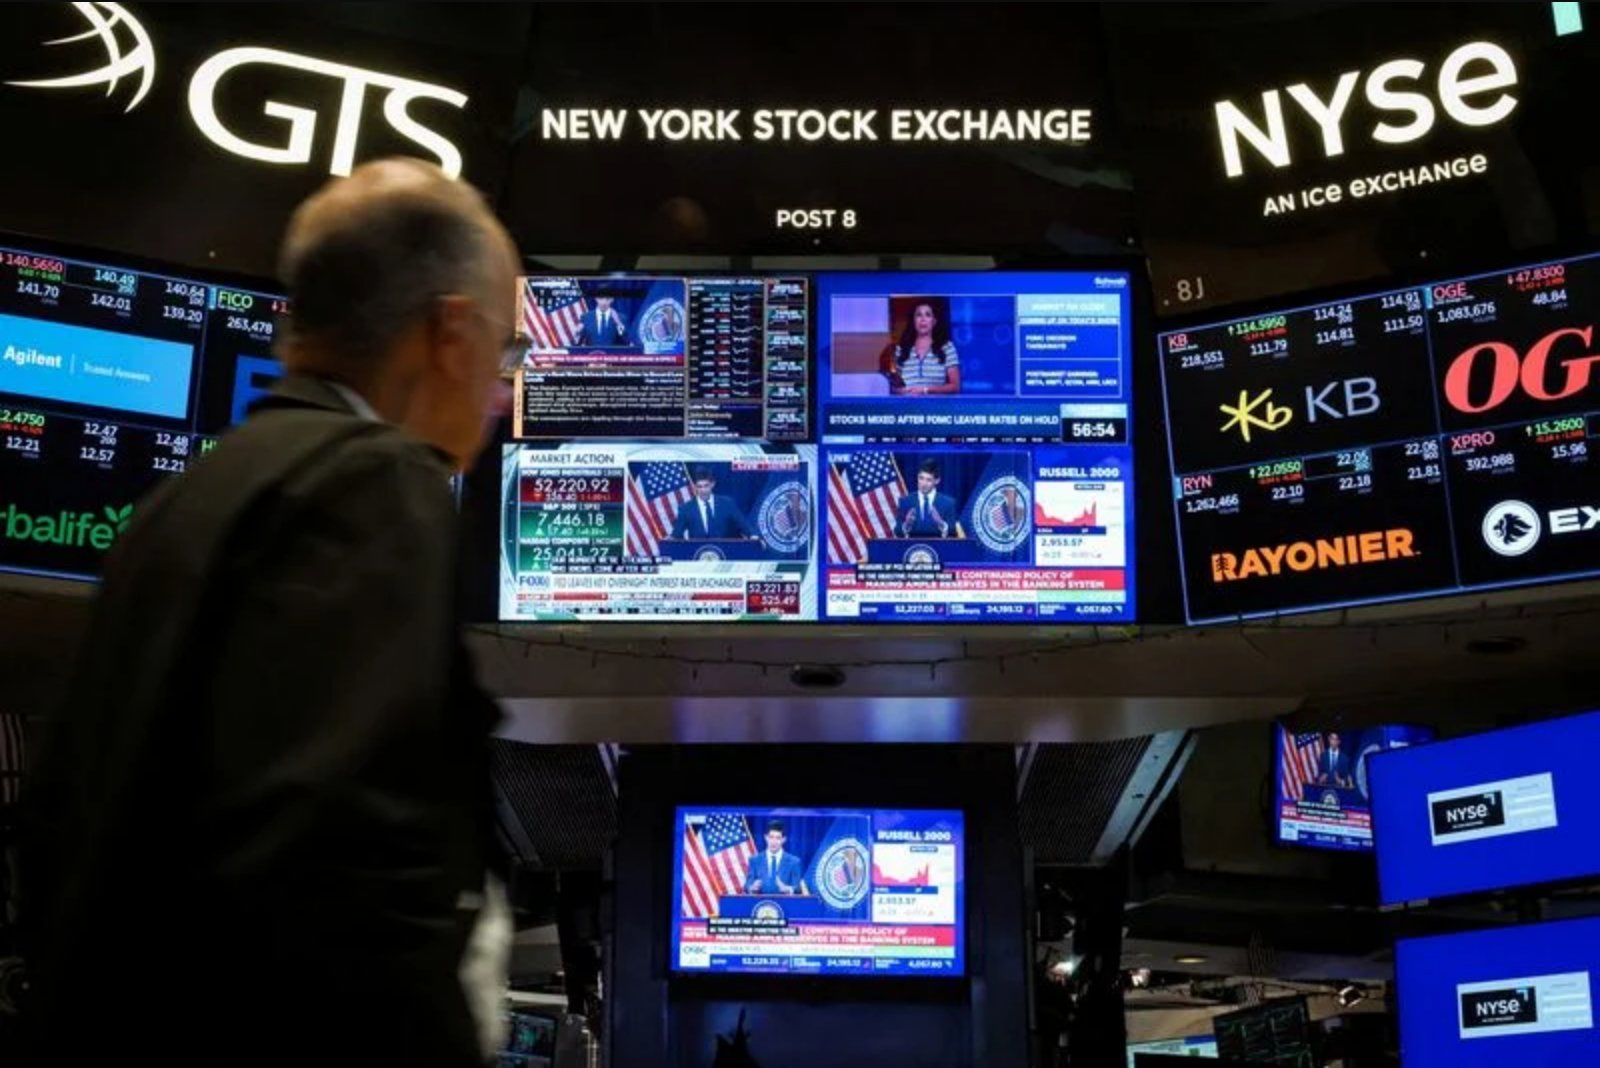
For much of the week, equities continued to demonstrate resilience to higher yields. Both the Nasdaq and the S&P 500 achieved new record highs on Tuesday, illustrating investors' willingness to look through the rise in borrowing costs and energy price volatility. However, markets softened later in the week as crude prices climbed and technology sector optimism faced fresh questions.
Chipmakers felt pressure after reports suggested OpenAI’s annualized revenue for September fell about $20 billion short of the company’s earlier indications. That development fed into the ongoing debate over whether the AI investment cycle can sustain current growth expectations. As quarterly results approach, analysts expect a notable slowdown from the extraordinary 50% earnings growth rate seen last quarter; LSEG data show consensus projections of roughly 30% growth for the coming reporting period.
Early earnings-related moves were mixed. Samsung Electronics saw its shares slip despite projecting a 783% jump in third-quarter operating profit, while TSMC recorded a record-high third-quarter revenue figure even as its shares eased. These results suggest that high headline numbers may be insufficient to fully satiate investor appetite if future guidance or demand signals disappoint.
Corporate borrowing and leverage tied to AI
Another development that should remain on investors’ radar is the scale of recent corporate debt issuance tied to AI-related strategies. Reported plans include Broadcom seeking to raise $50 billion in financing and SpaceX preparing to issue $30 billion of investment-grade debt while also arranging $10 billion in loans to purchase chips from Nvidia, which is a major shareholder in SpaceX. The sheer size of these financing moves raises questions about credit markets' capacity and the broader implications for corporate balance sheets.
Is this a turning point for markets?
The modest equity pullback on Thursday could represent a nascent inflection, or simply another transient blip in markets that have largely ignored the yield spike so far this year. Historical patterns suggest it is unlikely that equities will continue to disregard rising yields indefinitely, but the critical question remains how long current tolerances will hold.
Emerging markets and policy shifts
In emerging markets, headlines were notable. Brazilian assets delivered historic gains on Monday after right-wing candidate Flavio Bolsonaro posted a stronger-than-expected result in the first round of the presidential election, leaving him the favorite to win the runoff on October 25. In Asia, India’s central bank raised its benchmark repo rate by 25 basis points to 5.5% on Wednesday - the country’s first rate increase in nearly four years - citing rising inflationary pressures.
Looking ahead
Market participants face a busy calendar next week. The third-quarter earnings season ramps up with a slate of reports from large US banks, and investors will get another read on price pressures through the September Consumer Price Index report due midweek. These releases, alongside ongoing geopolitical developments and large-scale corporate financing plans, should help determine whether the recent detente between equities and yields endures.
Questions under discussion by columnists
- Will AI labs ever be able to turn a profit?
- Should we start thinking about "S&P 10,000"?
- Why might a potential ECB leadership change be bad news for France?
- Will central banks be good cops or bond villains?
- How did renewables help keep the lights on in the US this summer?
- Could Europe’s electoral calendar be the death knell for its economic reform push?
- Will the China-India diplomatic thaw lead to larger economic shifts?
- Why isn’t the price of tin falling back to earth?
- Which country could take advantage of China’s pullback in fuel exports?
- What tectonic shift is occurring in the zinc market?
- Could coal shipments stage a fourth-quarter rebound?
If you have feedback, the newsletter invites direct contact: "I’d love to hear from you, so please reach out to me at ." Readers can also sign up to receive the daily briefing in their inbox.