
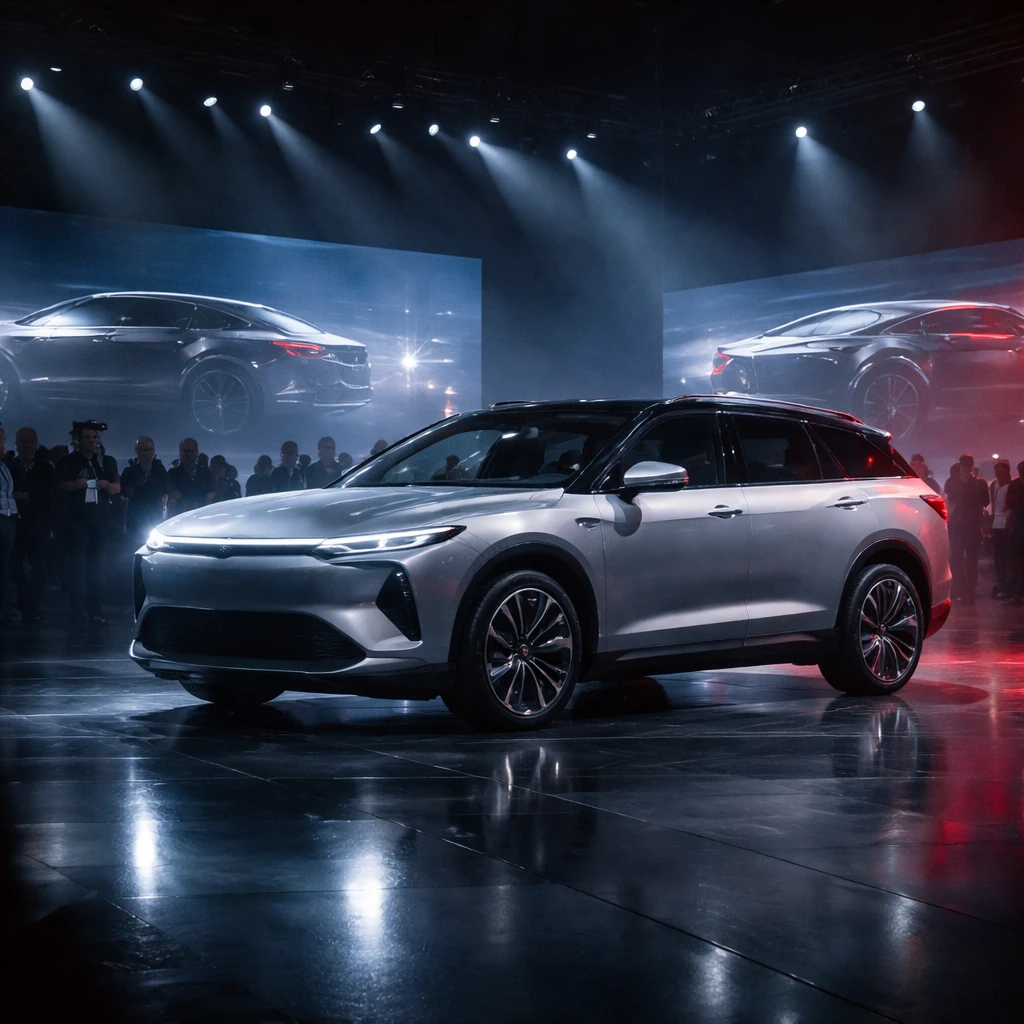
Xiaomi's stock price slipped sharply after the company held a product launch for its SkyNomad SUV lineup on the evening of July 30. Shares dropped nearly 6.9% to HK$28.90 as investors reacted to the event and its implications for Xiaomi's profitability and growth trajectory.
At the event Xiaomi presented two new extended-range electric vehicles: the flagship N90 Max, a seven-seat model priced at 299,900 yuan, and the N70 Max, priced at 259,900 yuan. Despite the high-profile reveal, the launch did not translate into fresh buying interest, particularly after the stock had already climbed substantially in the days leading up to the event.
Market participants flagged the pricing of the new SUVs as a renewed reminder of the tight margins that could weigh on Xiaomi's bottom line in coming quarters. Xiaomi is operating in a highly competitive environment, engaged in a major price war with Chinese EV rivals that are all vying to maintain market share in the world's largest EV market. That competitive pressure raises questions about the profitability of aggressive pricing strategies.
Delivery performance is another area of concern. Xiaomi's EV sales for the first half of the year reached only about one-third of the company's full-year target, creating skepticism about whether the new SUV models will be sufficient to meaningfully boost deliveries for the remainder of the year.
Analysts have responded by materially lowering earnings estimates for the fiscal year 2026. Consensus forecasts for both revenue and earnings per share have been cut in recent weeks, and the consensus price target has been reduced. These downward revisions reflect reassessments of Xiaomi's near-term growth and margin prospects.
The company's share buyback programme, which remains largely unused, has offered limited support to the stock. Approximately 89% of the buyback authorisation is still unspent, leaving only modest structural support from repurchases. At the same time, rising memory chip costs are squeezing smartphone margins, pressuring Xiaomi's core revenue stream.
Concerns focused on Xiaomi's EV ambitions contributed to the stock substantially underperforming broader Asian technology gains on Friday, as investors favored peers with clearer near-term earnings visibility.
Key points
- Xiaomi shares fell nearly 6.9% to HK$28.90 after the SkyNomad SUV launch on July 30.
- The N90 Max and N70 Max were priced at 299,900 yuan and 259,900 yuan, respectively, but the launch did not generate fresh buying momentum.
- Margin pressures from EV pricing and rising memory chip costs threaten profitability, while first-half EV deliveries reached only about one-third of the full-year target.
Sectors impacted
- Automotive - electric vehicles
- Consumer electronics - smartphones
- Semiconductors - memory chips
Risks and uncertainties
- Thin EV margins due to competitive pricing could hurt Xiaomi's overall profitability - affects automotive and consumer electronics sectors.
- First-half EV sales reaching only about one-third of the full-year target raises uncertainty over the company's ability to scale deliveries - affects investor confidence in automotive revenue projections.
- Rising memory chip costs continue to compress smartphone margins, threatening Xiaomi's core revenue engine - impacts semiconductor and consumer electronics sectors.